HARARE — Pfuma Fund’s US$8.71 million property development pipeline is entering its most consequential phase as the Zimbabwean real estate investment trust shifts from deploying capital to proving that its new assets can generate enough recurring rental income to sustain distributions.
The fund has spent much of 2026 converting cash into property, with capital work in progress rising to US$8.71 million by June 30 from US$3.59 million three months earlier. Over the same period, money-market investments fell to US$12.72 million from US$19.73 million.
The shift marks a fundamental change in Pfuma’s earnings model.
During the first half, the fund generated US$1.53 million in total income, with rental income contributing US$796,638 and investment income US$732,188. According to Equity Axis, investment income accounted for roughly 48% of the fund’s first-half income, underscoring the role that undeployed capital has played in supporting earnings and distributions.
That cushion is now shrinking.
As cash is committed to buildings in Ruwa, Kwekwe, Chivhu and Enterprise, Pfuma must increasingly rely on physical properties, tenants and leases to replace the investment returns generated by surplus cash.
The test for the fund is no longer whether it can deploy capital. It is whether that capital can produce cash.
Cork Road is the first test
The immediate test will come from Cork Road, a fully occupied property acquired through the issuance of 69.4 million additional units to the seller.
The transaction increased Pfuma’s unit base by 12.84%, while management expects rental income per unit to rise by 16.71%.
That difference is important.
For existing investors, an acquisition is economically accretive only if the additional income generated by the property exceeds the dilution created by issuing new units.
Cork Road is expected to begin contributing income from the third quarter, giving investors an early indication of whether Pfuma’s acquisition strategy is translating into higher distributable earnings.
The fund declared US$623,548 for the June quarter, equivalent to 0.1323 US cents per unit and representing 95% of distributable income. First-half distributions reached approximately US$1.07 million.
The challenge is that a significant portion of the income supporting those distributions has historically come from capital awaiting deployment.
Development pipeline becomes critical
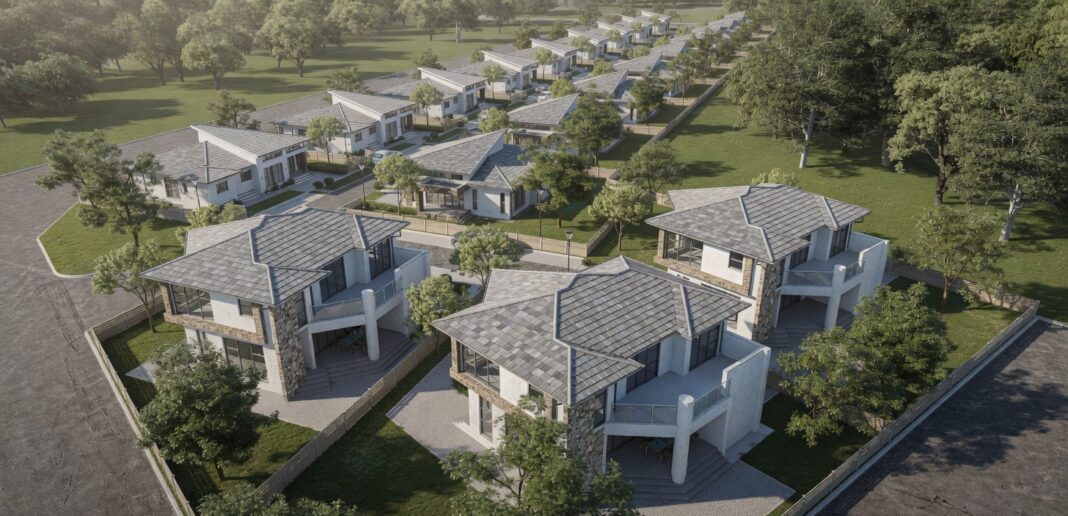
Pfuma’s largest current capital commitments are concentrated in Ruwa and Kwekwe, where US$6.14 million has been deployed and completion is scheduled for the fourth quarter of 2026.
Chivhu, representing US$1.84 million, is expected to be completed in the first quarter of 2027, while Enterprise is scheduled for the second quarter.
Those dates now matter more than the size of the pipeline itself.
A completed building does not automatically produce distributable income. The economic conversion requires tenants, signed leases, occupation and actual rental collections.
That makes construction execution and tenant acquisition just as important to investors as the original capital-raising exercise.
Analysts shift focus to income quality
The issue reflects a broader change taking place in Zimbabwe’s property and capital markets.
Industry experts who have spoken to The Zimbabwe Financial Mail have increasingly emphasised that investors are moving beyond headline asset growth and examining whether property developments can produce dependable cash flows and sustainable returns.
The Financial Mail has reported that institutional investors are showing greater interest in professionally managed property assets as Zimbabwe’s real estate market becomes increasingly diversified.
That evolution is significant for REITs.
The attraction of the structure is not simply exposure to property appreciation. Investors expect recurring income, efficient capital allocation and distributions that can be sustained through the property cycle.
Pfuma therefore faces a higher standard of scrutiny as its portfolio expands.
Cash flow becomes the real metric
Pfuma reported an operating cash-flow outflow of US$66,334 for the six months, following a US$1.04 million net VAT claim relating to Cork Road that increased receivables.
Excluding that timing effect, management calculated operating cash generation at US$976,161, equivalent to 87% of distributable income.
That distinction will become increasingly important.
As money-market investments decline, the fund will have less interest income available to supplement rental earnings. The underlying property portfolio must consequently generate sufficient cash to fund operating expenses, capital requirements and distributions.
This is where Pfuma’s investment proposition moves from balance-sheet strength to operational performance.
Zimbabwe’s property market provides the backdrop
Pfuma’s expansion comes against a backdrop of structural changes in Zimbabwe’s property economy.
The country’s prolonged currency instability and limited availability of long-term financing have historically made institutional property investment difficult. The emergence of US-dollar-denominated REITs on the Victoria Falls Stock Exchange is providing an alternative mechanism for investors seeking exposure to commercial real estate and hard-currency income.
At the same time, economic activity is becoming increasingly dispersed beyond traditional central business districts, creating opportunities in suburban commercial nodes and secondary cities.
Ruwa, Kwekwe and Chivhu fit into that broader investment thesis, but their success will ultimately depend on whether surrounding economic activity can support sustained tenant demand.
For Pfuma, location is therefore only part of the equation.
The more important question is whether the developments can generate contracted, collectible and recurring rental income.
The next results could redefine the investment case
Pfuma’s next financial results will provide the clearest indication yet of whether the strategy is working.
Investors will be looking beyond headline revenue and asset values towards project completion, tenant commitments, contracted rental income, yields, remaining development expenditure and cash generated from operations.
Cork Road should provide the earliest evidence.
Ruwa and Kwekwe will then determine whether Pfuma can successfully convert its largest development commitments into a durable rental base.
If the projects come on stream on schedule and achieve targeted occupancy, Pfuma will be able to progressively replace investment income with recurring property earnings.
If delivery is delayed or tenant demand falls short, however, the fund could face a temporary earnings gap as cash is tied up in non-income-producing assets.
The investment story has therefore entered a new phase.
Pfuma has demonstrated that it can raise and deploy capital.
It must now demonstrate that it can turn buildings into cash, and cash into sustainable distributions.