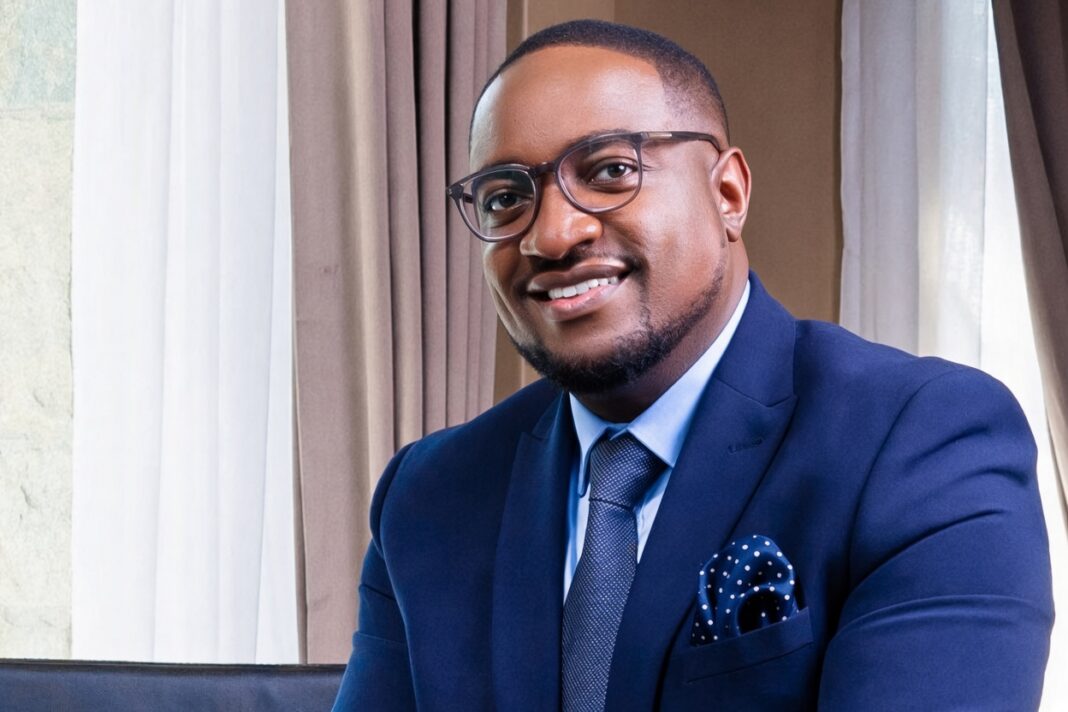
HARARE — ZB Financial Holdings is turning to fintech veteran Arthur Matsaudza to convert years of investment in digital banking into measurable growth in deposits, lending, efficiency and shareholder returns.
Matsaudza will take over as chief executive of ZB Bank on October 1, 2026, bringing with him more than 17 years of experience across banking, telecommunications, digital finance and financial technology.
His appointment represents a strategic shift for ZB at a time when the bank has largely completed the first phase of its digital transformation — upgrading the channels through which customers access financial services — and now faces the more difficult task of making those investments pay commercially.
Matsaudza’s career gives him experience across much of that value chain.
He founded and served as managing director of O’mari, Old Mutual’s fintech operation, and previously served as the group’s executive responsible for digital and data across African markets. He also held senior positions at Steward Bank, including head of digital banking and chief technology officer, following earlier experience in telecommunications.
The combination gives him exposure to technology infrastructure, digital product development, customer acquisition and financial services — areas that are becoming increasingly interconnected in banking.
Equity Axis said Matsaudza’s appointment comes as ZB enters a more commercially demanding phase of digital transformation, where the emphasis will increasingly shift from digital adoption to the impact technology has on deposits, credit growth, costs and profitability.
That distinction is important.
ZB has already invested in its customer-facing infrastructure, including its MyZB platform and digital access through mobile applications, USSD and WhatsApp.
The next question is whether those channels can fundamentally alter the economics of the bank.
For investors, the number of customers using a digital platform is less important than what those customers contribute to the balance sheet.
A digitally acquired customer can provide deposits without the cost associated with traditional branch-led acquisition. Transaction data can provide additional information for credit scoring and customer segmentation, while digital loan origination can reduce processing costs and accelerate lending decisions.
Automation can also reduce the cost of servicing accounts, processing payments and managing collections.
The potential therefore extends well beyond transaction fees.
ZB generated ZWG924 million in banking commissions and fees during the first half of 2026, compared with ZWG905 million in the corresponding period.
The increase reflects greater digital activity and customer acquisition, but regulatory pressure on banking charges means fee growth alone is unlikely to provide a sufficient long-term digitalisation strategy.
The bigger prize is balance-sheet expansion.
ZB Bank’s profit after tax reached ZWG88 million in the first half of 2026, while sustainable profit after tax improved to ZWG18 million from a ZWG44.3 million loss a year earlier.
At the same time, assets increased to ZWG14.67 billion from ZWG11.79 billion at December 2025.
Deposits and other funding rose to ZWG8.92 billion from ZWG6.57 billion over the same period.
For Matsaudza, the challenge will be to make that expansion more productive.
Growth in deposits must translate into appropriately priced lending. Greater use of customer data should improve credit selection and risk management. Digital origination should reduce the friction associated with borrowing, while automation should lower the cost of operating the enlarged balance sheet.
That is where his fintech background becomes strategically relevant.
At O’mari, Matsaudza was operating within the faster-moving part of financial services, where product design, technology and customer acquisition are closely integrated.
At ZB, those capabilities must now operate within a regulated full-service banking environment.
The opportunity is potentially broader because ZB Financial Holdings can connect banking with insurance and investment products, allowing digital platforms to become distribution channels across the group rather than simply banking applications.
That could increase customer lifetime value while reducing the cost of cross-selling.
The bank’s digital strategy also needs to address an increasingly important question in African financial services: who owns the technology capability?
Banks can purchase software, cloud infrastructure and specialist services from external vendors, but long-term competitiveness increasingly depends on their ability to integrate those systems, exploit proprietary data and develop products without excessive dependence on third parties.
Engineering, cybersecurity, data science and product-management capabilities will therefore become as important to ZB’s competitiveness as the digital platforms customers see.
Zimbabwe’s banking sector provides evidence of the potential value of such capabilities.
NMBZ’s development of XPlug Solutions illustrates how technology created to support internal banking operations can evolve into a broader commercial capability serving clients beyond the original institution.
ZB does not have to reproduce that model.
Instead, the strategic lesson is that technology can become an asset in its own right when banks develop sufficient internal expertise to control, integrate and commercialise it.
Matsaudza’s previous experience building O’mari gives ZB an executive who understands that distinction.
The regulatory environment is likely to reinforce the pressure for greater efficiency.
As banks face constraints on routine transaction charges, increasing volumes at lower unit costs becomes critical. Institutions need to deepen customer relationships, mobilise deposits and convert those deposits into productive assets without allowing operating costs to rise at the same rate.
Digitalisation is therefore becoming less about convenience and more about banking economics.
For ZB shareholders, Matsaudza’s tenure should ultimately be judged against a relatively straightforward set of indicators.
Can digital acquisition accelerate deposit growth? Can data improve credit quality and pricing? Can automation reduce the cost-to-income burden? Can ZB develop products faster? And can internally controlled technology create a competitive advantage rather than simply another operating expense?
Those questions provide a more meaningful measure of digital transformation than app downloads or transaction volumes.
ZB has already made substantial changes to the customer interface.
The next phase under Matsaudza will be measured deeper inside the institution — in the quality of its deposits, the productivity of its lending book, the efficiency of its operations and the returns generated from its technology investments.
In that sense, his appointment is not simply a change of leadership.
It is a test of whether ZB can turn digital banking from a customer-service proposition into a core engine of balance-sheet growth and profitability.