Zimbabwe’s economy has acquired an unusual characteristic: it appears capable of expanding substantially without necessarily producing a corresponding increase in factories, employment, electricity generation or household purchasing power. Over the past 15 months, successive revisions to gross domestic product (GDP) have transformed the official picture of the country’s economic size, culminating in the government’s latest estimate of US$66 billion.
By Brighton Musonza
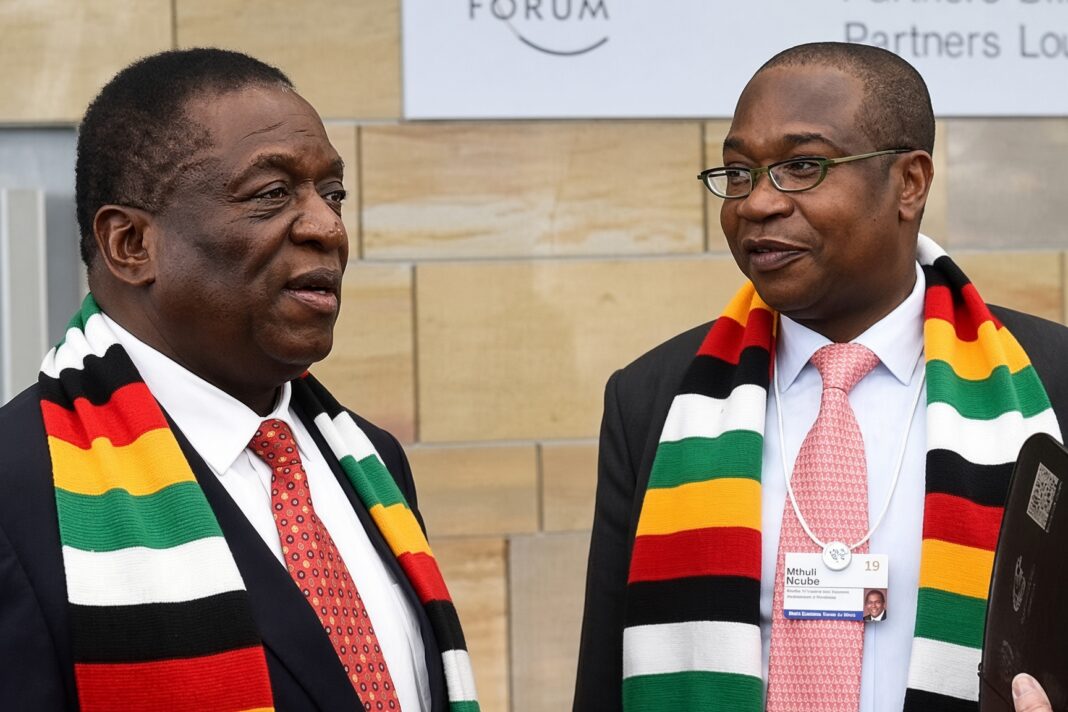
President Emmerson Mnangagwa and Finance Minister Mthuli Ncube presented the figure at the recent ZANU-PF conference, with Ncube observing that the economy had more than doubled in size since 2017. The claim is politically attractive, particularly for a government seeking to demonstrate the economic dividends of its reform programme. Economically, however, it requires a more careful distinction between genuine growth, changes in prices and exchange rates, and revisions to the statistical methods used to measure national output.
GDP measures the monetary value of final goods and services produced within an economy over a given period. It is not a measure of national wealth, government revenue or the amount of money circulating through the banking system. More importantly, an upward revision in GDP does not necessarily mean that additional economic activity has suddenly occurred. Sometimes statisticians simply become better at measuring what was already there.
That distinction is particularly relevant to Zimbabwe, where informal commerce, small-scale mining, agricultural production, transport services and household enterprises account for a substantial share of economic activity. An economy with extensive informal production can be systematically underestimated when national accounts depend heavily on registered companies, formal employment records and conventional tax data.
The Zimbabwe National Statistics Agency’s economic census, announced in July 2025, raised the estimated size of the economy from US$35.2 billion to US$44.4 billion. By October, Treasury was projecting GDP of US$52.3 billion for 2025, subsequently refined to US$52.4 billion in the 2026 National Budget. Another statistical rebasing exercise in June 2026 placed 2025 output at approximately US$59.7 billion. The latest political pronouncements have taken the figure to US$66 billion.
These numbers should not automatically be treated as contradictory. They may refer to different accounting years, statistical bases, price assumptions and exchange-rate conversions. Nevertheless, the frequency and scale of the revisions create an obvious challenge for analysts attempting to distinguish changes in economic performance from changes in economic measurement.
In national accounting, rebasing updates the reference year, production structures and statistical information used to estimate economic output. It can incorporate previously overlooked industries, revised business surveys and more comprehensive assessments of informal activity. Such revisions are internationally accepted and, when conducted transparently, improve economic measurement rather than undermine it.
Nigeria offers an instructive precedent. In 2014, a rebasing exercise increased its estimated GDP by approximately 89%, reflecting previously underrepresented telecommunications, entertainment and service industries. Nigeria became Africa’s largest economy virtually overnight, although the exercise did not suddenly create new factories, incomes or productive assets. It revealed economic activity that existing statistics had failed to capture.
Zimbabwe’s circumstances are comparable in one respect: its statistical infrastructure has struggled to keep pace with structural changes in production, particularly the growth of informal enterprises and the increasing importance of small-scale gold mining. Better measurement is therefore welcome. But statistical expansion should never be confused with an equivalent increase in real economic output.
The latest ZimStat figures nevertheless provide evidence of genuine economic recovery. The agency reported real GDP growth of 8.29% in 2025, with agriculture expanding by 27.9%, electricity by 14.9%, and mining and transport each by 10.4%. Manufacturing accounted for 16.8% of GDP, followed by mining at 15.9% and agriculture at 11.1%. These figures suggest that Zimbabwe’s economic expansion cannot be dismissed as an accounting exercise.
The difficulty arises when nominal GDP is presented as evidence of equivalent real growth. Nominal GDP measures production at current prices, while real GDP removes the effects of price changes. Zimbabwe’s multicurrency system introduces an additional complication because converting ZiG-denominated output into US dollars depends on the exchange rate selected. Consequently, movements in the exchange rate, domestic prices and statistical coverage can alter the dollar valuation of the economy without producing an equivalent change in physical output.
There is also an important distinction between nominal GDP and purchasing-power-parity GDP. The latter adjusts for differences in domestic price levels and is useful when comparing living standards and the purchasing power of incomes across countries. It is not interchangeable with nominal GDP measured at market exchange rates. The IMF’s April 2026 figures illustrate the difference: Zimbabwe’s projected nominal GDP was US$56.7 billion, against approximately US$149.7 billion on a purchasing-power-parity basis. Both estimates describe the same economy, but answer fundamentally different questions.
The World Bank’s published estimate of US$51.2 billion for 2025 further demonstrates the variation between institutional assessments. Such differences are not necessarily evidence of statistical incompetence; they can reflect different reporting periods, data revisions and forecasting assumptions. However, policymakers should explain these differences rather than selectively deploy whichever estimate presents the most favourable economic narrative.
The implications extend well beyond political communication. GDP is the denominator in several important measures of macroeconomic sustainability, including public debt, tax revenue, fiscal deficits and investment. Consider a country carrying US$20 billion in public debt. At GDP of US$45 billion, its debt-to-GDP ratio is approximately 44%. Revalue the same economy at US$66 billion and the ratio falls to about 30%, even though not a single dollar of debt has been repaid.
This is what economists call a denominator effect. It can improve headline fiscal ratios without changing the underlying capacity of government to service its obligations. The World Bank has specifically cautioned that national accounts revisions can materially alter fiscal indicators expressed as percentages of GDP.
For Zimbabwe, where external arrears, sovereign risk and limited access to international capital remain significant constraints, this distinction is particularly consequential. Creditors are ultimately concerned with foreign-exchange earnings, fiscal revenue, debt-servicing capacity and the credibility of economic institutions. A larger GDP estimate may improve certain solvency indicators, but it does not automatically increase export receipts or replenish Treasury’s bank accounts.
The same reasoning applies to private investment. A US$66 billion economy should, in principle, offer a larger addressable market for banks, telecommunications companies, retailers, manufacturers and infrastructure investors. Yet market size alone is insufficient. Investors examine disposable incomes, electricity reliability, access to foreign currency, enforceability of contracts and the cost of capital. An informal trader’s economic contribution may be captured in GDP without necessarily creating a bankable enterprise capable of attracting long-term investment.
Indeed, Zimbabwe’s substantial informal economy presents a deeper structural problem. Informality can support livelihoods and contribute meaningfully to national output, but much of that activity operates outside conventional credit, taxation and social protection systems. The challenge is not merely to count informal production more accurately. It is to create incentives for enterprises to accumulate capital, improve productivity, formalise operations and participate in larger domestic and international value chains.
This is where economic development theory becomes relevant. Robert Solow’s neoclassical growth framework emphasises capital accumulation, labour and technological progress as determinants of output, while endogenous growth theory places greater emphasis on innovation, skills and knowledge. Neither framework suggests that statistical reclassification constitutes a substitute for productivity growth.
Zimbabwe’s economic potential is considerable, particularly in mineral beneficiation, commercial agriculture, renewable energy, manufacturing and financial services. But transforming that potential into sustained increases in national income requires investment in productive capital, technological capability and institutional efficiency.
The country’s electricity sector offers a practical illustration. Energy Minister July Moyo’s reference to expanding the economy to US$45 billion during a recent solar project ceremony may have reflected a different economic benchmark, but it also exposed the need for consistency in official communication. More fundamentally, the minister’s emphasis on electricity supply was economically sound. An economy cannot indefinitely expand its industrial base without a corresponding increase in reliable and competitively priced energy.
There is a further distributional question. GDP growth does not establish who benefits from economic expansion. A mining sector can generate substantial export earnings and increase measured output while creating relatively few jobs if production is capital-intensive and domestic supply-chain linkages remain weak. Similarly, rising agricultural output can improve national accounts without producing lasting rural prosperity unless farmers gain access to irrigation, storage, markets and affordable finance.
The central issue is therefore not whether Zimbabwe’s economy is worth US$45 billion, US$59.7 billion or US$66 billion. It is whether the country is building the productive institutions, infrastructure and financial depth required to sustain a larger economy.
There are encouraging signs in the recovery of agriculture, mining and manufacturing, alongside efforts to restore monetary stability and rebuild international financial relationships. The IMF’s 2026 staff-monitored programme provides a framework for strengthening macroeconomic credibility, although its projections remain distinct from the government’s latest headline estimates.
Ultimately, Zimbabwe needs a transparent and consistent national accounts framework, with clearly identified base years, reconciled historical series and explanations of the exchange rates used in converting domestic output into US dollars. Statistical revisions should be treated as technical improvements, not political milestones.
A larger measured economy can improve the country’s investment narrative. A more productive economy can improve the lives of its citizens. The two are related, but they are not synonymous.
Zimbabwe may indeed be substantially wealthier in productive activity than its older statistics suggested. The real economic achievement, however, will come when that statistical wealth translates into higher real wages, deeper capital markets, competitive industries, reliable infrastructure and stronger public finances.
An economy does not become prosperous simply because its GDP has been revised upwards. It becomes prosperous when its people and businesses can produce more, earn more and invest more. That is the expansion Zimbabwe should be measuring most carefully.
Brighton Musonza: MBA(UK), BSc Business Management (UK). Fellow Chartered Management Institute (FCMI), Business Analytics Diploma, IIBA Certified Business Analyst (CCBA) and SAP Technologies. Contact details: musomusonza@gmail.com.