HARARE — Masimba Holdings has entered the second half of 2026 with a US$320 million order book, but the Zimbabwean construction group is facing a familiar problem: winning infrastructure work faster than customers are paying for it.
The ZSE-listed contractor’s half-year results to June show the growing gap between its pipeline of contracted work and the cash being converted from projects already under execution.
Revenue fell 13% to US$25.4 million from US$29.2 million a year earlier, while profit after tax declined by about 6% to US$2.74 million. Earnings per share fell 5.7% to US$1.15.
Yet the order book expanded to approximately US$320 million at June, up from US$278 million at December and US$301 million in June 2025. Only about 9.1% of the secured order book had been converted into revenue during the first half.
Fincent Securities, in its October 8 earnings review, described the central investment issue bluntly: “Masimba is winning work faster than its clients are paying for it.” The broker initiated coverage with a HOLD recommendation and a 12-month target price of US$0.10, equivalent to ZWG2.68 at the report’s reference exchange rate.
The tension is most visible in Masimba’s working capital. Cash generated from operations was negative US$0.8 million during the half, compared with US$3.4 million in the comparable period, while contract receivables and work in progress rose to US$58.9 million.
The company had enough work to keep its construction fleet busy, but the conversion of that work into cash remained slow. Contract receivables represented about 373 days of revenue, compared with 320 days at December 2025.
Analysts who spoke to The Zimbabwe Financial Mail said Masimba’s results illustrate a broader weakness in Zimbabwe’s infrastructure investment model: project awards are not the same thing as economic activity until funding, execution, certification and payment move through the project cycle.
They said the country’s infrastructure requirements remain substantial, particularly in roads, mining, energy, water and housing, but the financing architecture behind those projects remains just as important as the projects themselves.
Masimba’s experience is particularly relevant because Zimbabwe is trying to increase infrastructure investment while simultaneously maintaining fiscal discipline. Government-funded projects can create substantial construction demand, but delayed disbursements or changes in payment arrangements can leave contractors carrying significant working-capital burdens.
That risk has already been visible in the construction sector. Masimba previously warned that government plans to pay contractors in ZiG created uncertainty around cash flow and project planning, although the company has continued to maintain a substantial order book.
The group has consequently been increasing its exposure to private-sector projects, particularly in mining. That strategy is becoming increasingly important as Zimbabwe’s mining sector attracts investment and companies expand production capacity.
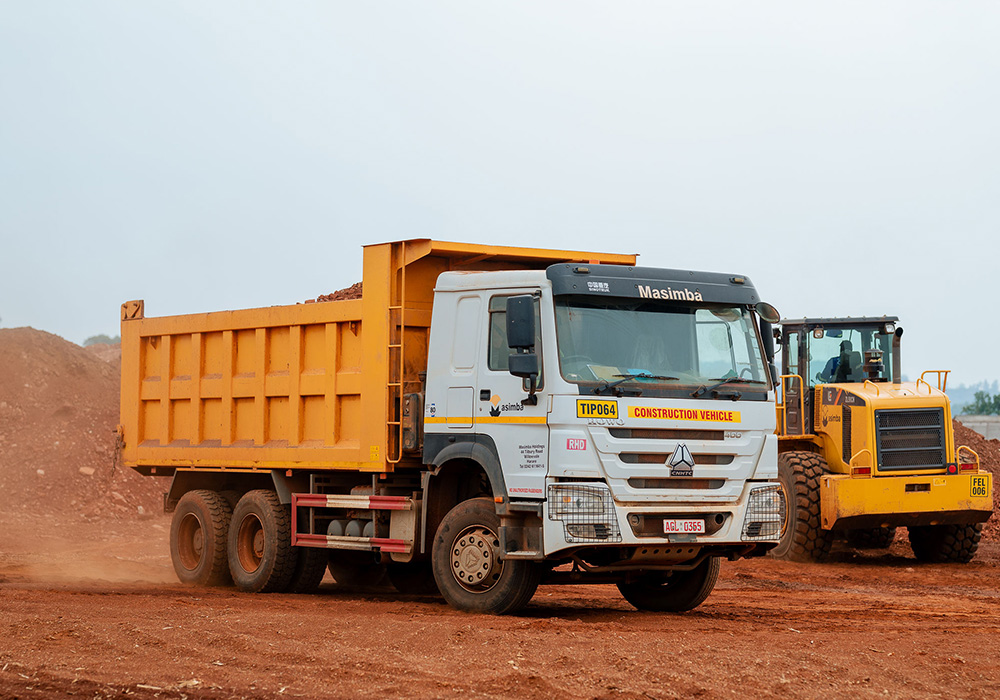
Masimba’s capital expenditure also reflects its confidence in the underlying demand. The company invested in additional hauling and trenching equipment during the year to increase operational capacity and improve project execution.
The half-year numbers show that operating performance was more resilient than the headline revenue decline suggests. EBITDA fell only modestly to US$6.3 million, with the EBITDA margin improving to 25% from 23.1% a year earlier.
That margin improvement indicates that Masimba has been able to protect profitability through cost control even as project execution slowed.
The problem is therefore less about a collapse in demand for construction services than the timing and quality of cash conversion.
This distinction matters in Zimbabwe’s current economic environment. Mining investment, road rehabilitation and other infrastructure projects are creating demand for contractors, while improved currency stability and lower inflation are making longer-term planning more predictable. But businesses still have to manage liquidity carefully in an economy where access to working capital remains constrained.
Masimba’s private-sector strategy is designed partly to address that problem. Private mining and commercial projects can diversify the customer base and potentially improve payment cycles, reducing dependence on government-funded infrastructure.
The company completed 16 kilometres of the Kezi-Maphisa Road during the period and opened the Chevron Bridge, while also executing projects in the mining sector. Its secured workload includes both public and private-sector projects.
For investors, however, the US$320 million order book cannot be treated as US$320 million of near-term revenue.
Fincent expects full-year 2026 revenue of about US$55.4 million, rising to US$62 million in 2027, illustrating the considerable time required to translate contracted projects into reported earnings.
The broker’s base-case valuation places Masimba at a US$0.10 target, with a potential upside case of US$0.145 if revenue accelerates, receivables normalise and the final dividend reaches US$0.50 a share.
The downside case is equally instructive: slower revenue conversion, receivables remaining elevated and no dividend could put pressure on the valuation.
For Zimbabwe’s broader economy, Masimba’s results underline a fundamental issue in infrastructure-led growth.
Zimbabwe does not simply need more projects. It needs projects that are financed, executed, paid for and converted into productive economic assets.
That distinction will become increasingly important as the government seeks to turn mining revenues, private investment and public infrastructure spending into higher productivity and long-term economic growth.
Masimba has the work. The next test is whether Zimbabwe’s infrastructure financing system can deliver the cash quickly enough for that work to become earnings, investment and economic output.