HARARE — Zimbabwe is preparing to seek its first sovereign credit rating as the Government attempts to convert recent gains in macroeconomic stability into a credible reduction in the country’s risk premium and, ultimately, renewed access to international capital.
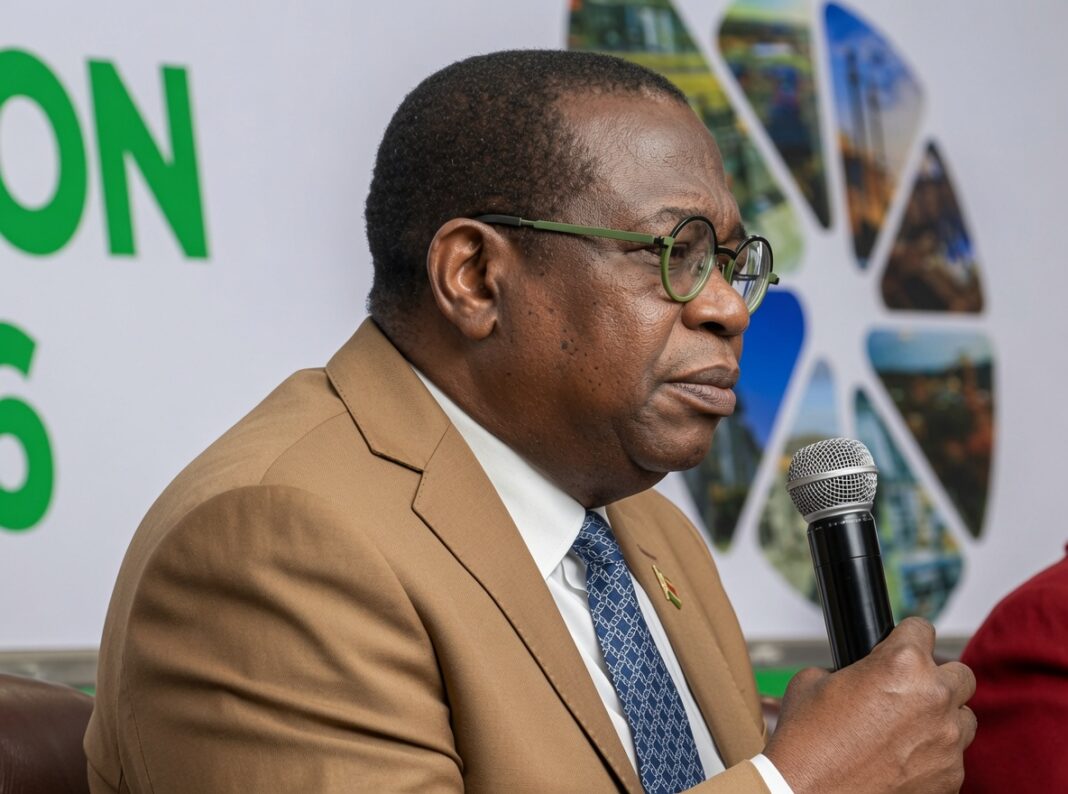
Finance Minister Mthuli Ncube announced the intention on Monday as he introduced President Emmerson Mnangagwa at the opening of Ecobank Zimbabwe’s new headquarters in Harare, placing the rating exercise within the broader programme of economic reform and international re-engagement.
The move comes at a critical juncture for Zimbabwe.
Economic growth, inflation and foreign-currency generation have improved markedly, but the country remains burdened by substantial public debt, external arrears and a history of policy instability that has kept it largely excluded from conventional international capital markets.
Equity Axis reported that the proposed sovereign rating would provide an external assessment of Zimbabwe’s creditworthiness at a time when Government is seeking to demonstrate that economic stabilisation is becoming structural rather than temporary.
Ncube said the economy grew by 8.3% in 2025 and is projected to expand by about 5% this year, with agriculture, mining and improving business conditions expected to remain important drivers.
Inflation has also undergone a substantial adjustment. Annual ZiG inflation stood at 3.2% in July, extending the period of single-digit inflation recorded during 2026.
Foreign-currency generation has strengthened at the same time. Ncube said receipts reached US$10.72 billion during the first half of the year, with full-year inflows expected to reach at least US$20 billion.
Trade data have provided additional support for the external position. Merchandise exports reached approximately US$1.47 billion in July against imports of about US$1.15 billion, producing a monthly trade surplus of roughly US$320.6 million.
But analysts caution that these improvements, while significant, do not by themselves constitute a sovereign credit turnaround.
“Zimbabwe is now at the point where macroeconomic stabilisation has to translate into balance-sheet credibility,” one economist told The Zimbabwe Financial Mail. “Rating agencies will look beyond the headline growth rate. They will want to know whether the country can consistently generate the foreign exchange and fiscal resources required to service its obligations.”
That distinction is crucial.
Zimbabwe’s public and publicly guaranteed debt was estimated at approximately US$22.8 billion at the end of 2025, according to IMF estimates. Of this, external public debt accounted for about US$15.2 billion, while external arrears to official creditors were estimated at US$7.7 billion.
The debt ratio alone, therefore, does not tell the full sovereign-risk story.
“Zimbabwe’s challenge is less about the headline debt-to-GDP number and more about the composition of the debt, the arrears and the country’s payment history,” a financial-market analyst speaking to The Zimbabwe Financial Mail said.
“The market is ultimately asking whether Zimbabwe can become a reliable borrower again. A rating will formalise that conversation, but it will not resolve it.”
Zimbabwe’s longstanding arrears to external creditors remain one of the principal obstacles to normalisation of relations with international lenders and capital markets.
The country has been working on a broader debt-resolution strategy while engaging international financial institutions under its re-engagement programme. The IMF Staff-Monitored Program has provided an additional mechanism for demonstrating policy discipline.
The Fund’s first review found that Zimbabwe had met its quantitative targets and structural benchmarks through the end of March, although an indicative target relating to protected social and priority expenditure was missed.
For rating agencies, the significance of such programmes extends beyond individual targets.
They provide evidence of whether fiscal and monetary reforms are becoming institutionalised and whether Government can maintain policy discipline over an extended period.
“The rating will be less about rewarding Zimbabwe for one good year and more about establishing whether the reform trajectory is durable,” another economist told The Zimbabwe Financial Mail.
“Investors will be looking for consistency. If inflation remains contained, reserves continue to build, fiscal policy remains disciplined and the debt-resolution process moves forward, the risk premium should eventually respond.”
A sovereign rating could therefore become an important piece of infrastructure for Zimbabwe’s eventual return to international capital markets.
It would provide banks, institutional investors and other creditors with a standardised external assessment against which Zimbabwe could be compared with other emerging and frontier markets.
However, the initial rating could also expose the extent of the country’s remaining vulnerabilities.
“A rating is not necessarily a badge of success,” the analyst said. “It can initially be a very uncomfortable mirror. If the rating comes in deeply speculative territory, Government will have to confront the reality that macroeconomic improvements have not yet translated into lower sovereign risk.”
That is why the trajectory following the initial rating could prove more important than the rating itself.
An eventual upgrade would require evidence of sustained improvements in debt sustainability, external liquidity, fiscal credibility, governance, institutional capacity and creditor relations.
The proposed rating also comes against the backdrop of Zimbabwe’s changing investment landscape.
The opening of Ecobank Zimbabwe’s new headquarters in Harare provides an illustration of the growing interest in the country’s longer-term commercial prospects. But banks and investors making long-duration commitments must price not only the opportunities presented by economic growth but also the risks associated with the sovereign environment.
Country risk ultimately feeds into the cost of capital across the economy.
A lower sovereign risk premium could eventually reduce borrowing costs for banks and corporates, improve the economics of infrastructure projects and make Zimbabwean assets more attractive to international investors.
The converse is equally true.
Until creditors become confident that Zimbabwe’s reform gains are durable, capital will continue to demand a substantial premium for assuming Zimbabwean risk.
For Ncube, the proposed rating is therefore another test of the Government’s re-engagement strategy.
Zimbabwe has begun improving several of the indicators that international investors watch most closely: growth has recovered, inflation has fallen, foreign-currency receipts have increased and the external trade position has strengthened.
The harder task is converting those gains into creditworthiness.
That will ultimately depend on whether Zimbabwe can resolve its arrears, restore debt sustainability, strengthen reserves, maintain fiscal discipline and demonstrate a sufficiently long record of predictable economic management.
“The real objective should not simply be to obtain a rating,” the first economist said. “The objective should be to create the conditions under which the rating improves—and with it, Zimbabwe’s cost of capital.”
For a country that has spent more than two decades largely outside international capital markets, that distinction could prove decisive.