HARARE — Zimbabwe’s two stock exchanges ended Friday’s trading session on contrasting trajectories, with the Zimbabwe Stock Exchange (ZSE) retreating as selling pressure weighed on selected industrial and consumer counters, while the Victoria Falls Stock Exchange (VFEX) advanced amid stronger trading activity in US-dollar-denominated securities.
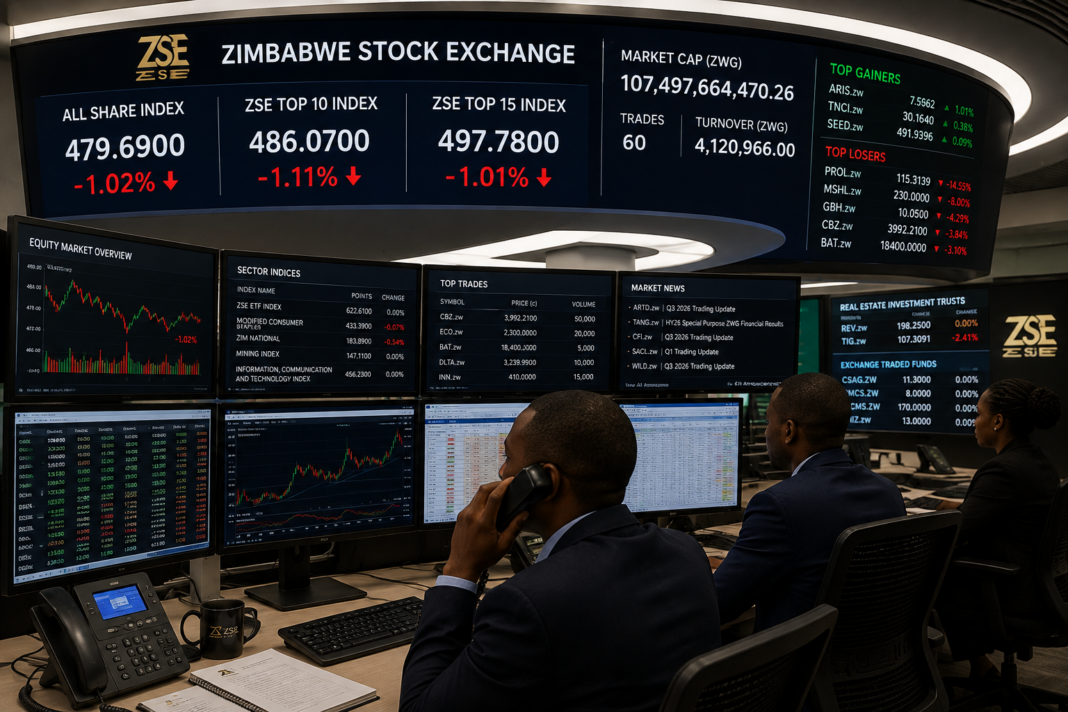
The ZSE All Share Index declined 0.55% to 475.30 points on October 16, 2026, as losses in Proplastics, Art Corporation, Rainbow Tourism Group and ZSE Holdings offset gains in selected mining and financial stocks.
The VFEX All Share Index, meanwhile, gained 0.67% to 271.75 points, extending the divergence between Zimbabwe’s local-currency and US-dollar equity markets.
Combined turnover across the two exchanges reached approximately US$2.45 million, calculated using the Reserve Bank of Zimbabwe’s official average exchange rate for the day.
The ZSE recorded turnover of ZWG19.61 million, equivalent to approximately US$737,000, across 101 trades.
The VFEX generated US$1.71 million from 154 trades, accounting for approximately 70% of the combined value traded.
The figures suggest that US-dollar-denominated securities continued to attract a substantial share of reported exchange turnover, although a single trading session is insufficient to establish a sustained shift in investor preferences.
ZSE figures converted at the RBZ average rate of ZWG26.6072 per US$1 on October 16. VFEX figures are reported directly in US dollars. Values are rounded.
ZSE market capitalisation settles near US$4.14 billion
The local-currency exchange closed with market capitalisation of ZWG110.02 billion, equivalent to approximately US$4.14 billion at the official average exchange rate.
The Top 10 Index declined 0.73% to 465.10 points, while the Top 15 Index shed 0.70% to 476.16 points.
The Top 25 Index fell 0.46% to 516.60 points.
The declines in the major indices suggest that weakness extended beyond a small number of lightly traded securities, although the magnitude of losses varied across sectors.
The Mid Cap Index provided a modest counterweight, gaining 0.10% to 551.27 points.
The Small Cap Index remained unchanged at 100.11 points.
The contrasting performance illustrates the uneven distribution of investor demand across the market.
While some companies benefited from buying interest, others experienced sharp price adjustments that pulled the broader indices lower.
Unifreight leads gainers with 12.5% rally
Unifreight Africa emerged as the session’s strongest performer, advancing 12.50% to 225.00 ZiG cents.
The transport and logistics group was followed by RioZim and TNC Industries, which each gained 5.56%, closing at 95.00 cents and 87.1956 cents respectively.
Zimre Holdings rose 3.02% to 72.25 cents, while Dairibord Holdings gained 0.62% to 606.00 cents.
Unifreight’s advance was notable because the company had issued a cautionary announcement on October 12.
Such announcements generally alert investors to developments that may affect a company’s securities, but the market data alone does not establish whether the announcement caused Friday’s price increase.
Without examining the full announcement and trading volumes for the individual counter, the reason for the gain cannot be determined conclusively.
The performance of RioZim also contributed to the positive movement in the Mining Index, which advanced 5.56% to 163.94 points.
Mining remains an important component of Zimbabwe’s economy, generating foreign-currency earnings and supporting demand for transport, engineering, energy and financial services.
However, share-price gains in individual mining companies should not be interpreted automatically as evidence of stronger production or earnings.
Proplastics, Art and Rainbow Tourism suffer heavy losses
The session’s most significant declines were concentrated in a group of industrial and consumer-facing businesses.
Art Corporation fell 14.96% to 17.90 ZiG cents, making it the day’s biggest percentage loser.
Proplastics followed with a 14.81% decline to 115.00 cents.
Rainbow Tourism Group lost 14.74% to close at 94.00 cents, while ZSE Holdings retreated 9.97% to 399.75 cents.
General Beltings Holdings declined 9.03% to 10.1429 cents.
These losses illustrate how sharply individual counters can move in a relatively small and sometimes thinly traded market.
A large percentage price movement does not necessarily indicate an equivalent deterioration in a company’s underlying financial position.
Prices can also respond to limited liquidity, the size of individual orders and changes in investor expectations.
For shareholders, however, the declines demonstrate the importance of distinguishing between business fundamentals and short-term market pricing.
Consumer discretionary stocks plunge nearly 15%
Sector performance revealed a particularly sharp divergence.
The Consumer Discretionary Index dropped 14.74% to 472.20 points, while the Materials Index declined 6.89% to 187.04 points.
The Real Estate Index lost 3.65%, and the Agriculture Index retreated 0.69%.
By contrast, the New Industrial Index gained 1.10%, the Mining Index rose 5.56%, and the Financials Index advanced 0.51%.
The Consumer Staples Index slipped a marginal 0.19%, while the Information, Communication and Technology Index remained unchanged.
The performance of consumer-facing securities is significant in Zimbabwe’s economic environment.
Household purchasing power, employment conditions and disposable incomes remain important determinants of demand for manufactured goods, tourism services and other discretionary expenditure.
However, Friday’s sector decline cannot by itself establish that consumer spending has weakened.
A more reliable assessment would require company earnings, sales data and broader economic indicators.
VFEX climbs despite Caledonia and Invictus losses
The VFEX provided a stronger overall performance, with its All Share Index gaining 0.67% to 271.75 points.
Market capitalisation reached US$8.97 billion, while turnover stood at US$1.71 million across 154 transactions.
The index advanced despite significant losses in several securities.
Invictus Energy recorded the steepest decline among the reported losers, falling 17.09% to US$0.1232 per share.
Caledonia Mining Corporation declined 6.20% to US$35.5038.
TSL Limited fell 2.55% to US$0.2100, Nedbank Group lost 1.96% to US$16.6667, and First Mutual Properties declined 1.22% to US$0.1131.
The gains elsewhere in the market were sufficient to leave the benchmark index in positive territory.
This illustrates why headline index performance must be considered alongside individual share movements.
A rising index does not necessarily mean that most listed companies advanced, particularly where market-capitalisation weights differ.
Invictus falls despite progress at Musuma-1
Invictus Energy’s 17.09% decline attracted attention because it coincided with fresh developments at the company’s Cabora Bassa exploration project in northern Zimbabwe.
The company announced that construction of the Musuma-1 wellpad had been completed and formally accepted by drilling contractor Exalo Drilling.
The milestone clears the way for the relocation of Exalo Rig 202 from the Mukuyu-2 site to Musuma-1.
Drilling remains scheduled to begin in November, subject to rig mobilisation, remaining maintenance work and final acceptance procedures.
The project forms part of Zimbabwe’s efforts to develop its domestic petroleum and natural gas potential.
A commercially viable discovery could eventually create opportunities for energy supply, industrial development and associated infrastructure investment.
However, exploration remains inherently uncertain.
Completion of a drilling site does not establish the presence of commercially recoverable hydrocarbons, and further technical work would be required before any production or revenue could be realised.
The decline in Invictus shares therefore should not be attributed to the operational announcement without evidence establishing that connection.
Investors may also be responding to broader financing, exploration or portfolio considerations.
Caledonia faces scrutiny over gold production
Caledonia Mining’s 6.20% decline comes as investors assess the operational performance of its Zimbabwean gold assets.
The company recently reduced its 2026 production guidance for Blanket Mine to between 69,000 and 72,500 ounces, from an earlier forecast of 72,000 to 76,500 ounces.
The adjustment followed production difficulties involving compressed-air capacity at deeper mining levels and delays in operational improvements.
Caledonia also revised its cost guidance upwards, increasing the expected all-in sustaining cost per ounce.
The development is important because gold mining profitability depends on the relationship between production volumes, operating costs and realised gold prices.
Higher international gold prices can support revenue, but lower output and rising production costs can offset part of that benefit.
For Zimbabwe, Caledonia remains significant as an established gold producer and investor in mining infrastructure.
The company also has interests in the Bilboes and Motapa projects, which could contribute to the country’s longer-term gold production capacity.
Nevertheless, Friday’s share-price movement cannot be attributed exclusively to the company’s revised guidance without further market evidence.
Monetary stability provides a changing investment backdrop
The contrasting performance of Zimbabwe’s exchanges comes against a backdrop of improved reported monetary stability.
The Reserve Bank of Zimbabwe’s latest figures show annual ZiG inflation at 3.70% in September 2026, with monthly inflation of 0.54%.
Annual US-dollar inflation stood at 3.46%, while monthly US-dollar inflation was 0.28%.
The official average exchange rate was ZWG26.6072 per US dollar on October 16, compared with ZWG26.6094 the previous day.
The small movement illustrates the relative stability of the official rate over the two sessions.
For businesses and investors, lower inflation and more predictable exchange rates can improve financial planning and reduce uncertainty in pricing, procurement and investment decisions.
However, the stability of monetary indicators does not automatically translate into stronger stock-market liquidity.
Equity markets also depend on the availability of investable savings, institutional participation, corporate earnings and confidence in the ability to enter and exit positions efficiently.
Why Zimbabwe’s two exchanges behave differently
The ZSE and VFEX operate within the same national economy but provide different currency exposures.
ZSE securities are priced and traded in ZiG, while VFEX securities are denominated in US dollars.
This distinction can influence investor behaviour.
Companies with substantial foreign-currency revenues may be particularly relevant to investors seeking exposure to export-oriented businesses.
The VFEX also offers a market structure designed around US-dollar settlement and capital raising.
The ZSE, meanwhile, remains an important platform for domestic investment and price discovery in local-currency securities.
Neither market is inherently insulated from economic risk.
US-dollar-denominated shares can decline because of weak earnings, adverse commodity prices, operational problems or changing valuations.
Likewise, local-currency shares can generate positive returns where business performance and market conditions are supportive.
The relevant distinction is therefore not simply between a stronger and weaker currency.
It is between different combinations of currency exposure, corporate fundamentals, liquidity and investor expectations.
Trading liquidity remains a structural challenge
Friday’s combined turnover of approximately US$2.45 million illustrates both the activity taking place across Zimbabwe’s exchanges and the relatively limited depth of the equity market.
The VFEX accounted for most of the value traded, despite having fewer transactions than the ZSE’s larger number of listed domestic counters.
Market turnover matters because it affects the ability of investors to buy or sell shares without causing substantial price movements.
Where trading volumes are limited, relatively small orders can produce significant percentage changes in individual securities.
This can increase volatility and complicate portfolio management for institutional investors.
For pension funds, insurance companies and other long-term investors, adequate liquidity is an important consideration alongside expected returns.
A deeper market can also improve companies’ ability to raise new equity capital for expansion.
Zimbabwe’s longer-term capital-market development will therefore depend not only on index performance but also on stronger trading participation, new listings, improved disclosure and a broader investor base.
Corporate announcements add to investor considerations
The ZSE’s latest corporate notices include Unifreight’s October 12 cautionary announcement and shareholder circulars issued by Meikles Limited on October 9.
Tanganda Tea Company also issued a notice concerning director appointments on October 8.
On the VFEX, the October 16 announcements included a notice to shareholders from Caledonia Mining and Invictus Energy’s Musuma-1 operational update.
WestProp Holdings had also published updates concerning its dividend arrangements, restructuring timetable and exit-offer results on October 15.
Corporate announcements can influence investor expectations by providing information about governance, capital allocation, operational developments and potential transactions.
However, investors must distinguish between announcements that have immediate financial consequences and those whose effects depend on future implementation.
Outlook: earnings and liquidity to determine market direction
Friday’s trading demonstrated that Zimbabwe’s stock market remains sensitive to company-specific developments and uneven liquidity.
The ZSE’s decline reflected pressure in selected industrial, materials and consumer-related counters, despite gains in mining and financial stocks.
The VFEX advanced even as Invictus Energy and Caledonia Mining experienced substantial losses.
For the coming sessions, investors are likely to focus on corporate announcements, earnings prospects, commodity-market developments and the availability of liquidity across both exchanges.
The broader economic environment remains relevant.
Zimbabwe’s reported improvement in inflation and exchange-rate stability provides a more predictable foundation for business planning, but sustained equity-market growth will require stronger corporate profitability and greater participation from domestic and international investors.
The challenge for Zimbabwe’s capital markets is to translate macroeconomic stabilisation into deeper pools of investable capital and more consistent financing for productive enterprises.
Friday’s contrasting performance was a reminder that a stable currency environment and rising headline indices are only part of that process.
Ultimately, the health of Zimbabwe’s stock market will depend on the earnings companies generate, the confidence investors place in those earnings and the depth of the market available to trade their shares.