HARARE – Zimbabwe-listed real estate investment vehicle Pfuma Fund increased its net distributable income by 14.6% in the third quarter ended September 30, 2026, supported by stronger rental receipts and the addition of new retail property assets, although investment income declined as the fund redirected cash towards development projects.
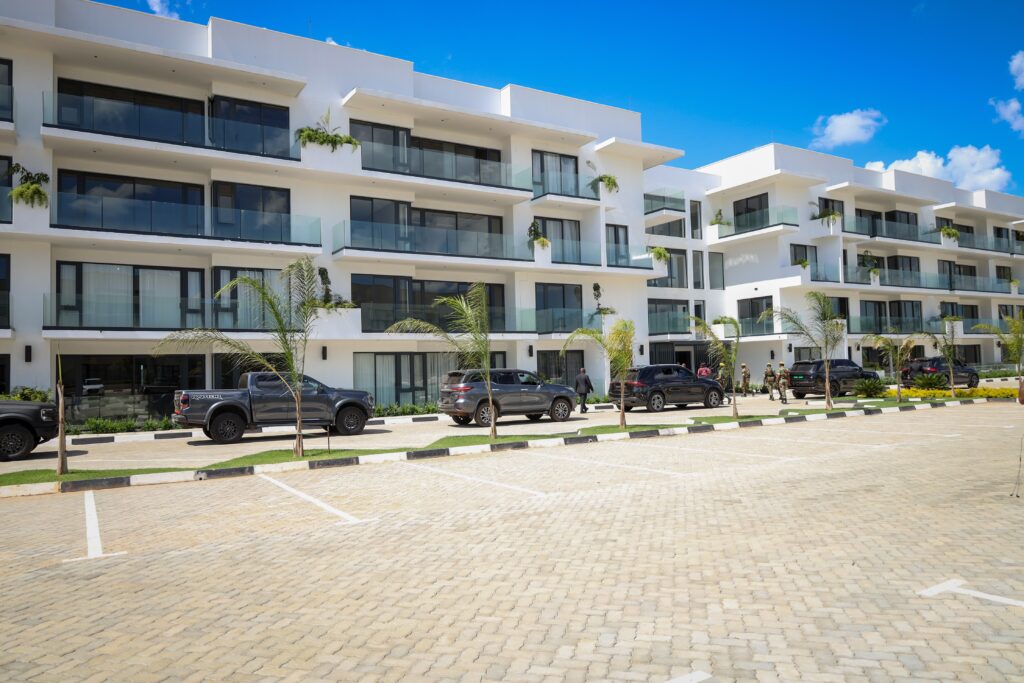
In an unaudited trading update dated November 10, Pfuma reported net distributable income of US$752,372 for the quarter, compared with the preceding quarter. Rental income rose 39.9% to US$648,049 from US$463,287, reflecting the addition of the Cork Road Quick Service and Casual Dining Centre and stronger variable rental income from its Chegutu property.
Total income reached US$965,134 during the quarter, comprising rental income of US$648,049 and investment income of US$317,085. Net property expenses amounted to US$45,335, while administrative costs were US$167,427.
However, investment income declined by 29% as Pfuma continued deploying funds held in interest-bearing investments into its development pipeline. The fund said this reduction was expected to reverse in coming quarters as completed developments begin generating rental income and replace short-term investment returns.
Year-to-date total income stood at US$2.49 million, while net distributable income reached US$1.88 million. The fund invested a further US$1.304 million in its development pipeline during the quarter.
Pfuma also declared an interim dividend of US$677,135 for the three months to September, equivalent to 90% of distributable income after taking account of regular maintenance expenditure at its properties. The distribution translates to 0.1252 US cents per unit.
The fund’s net asset value stood at US$54.07 million, with 540.75 million units in issue.
The trading update points to a property market increasingly shaped by demand for income-generating assets and the search for investment opportunities capable of preserving value in a predominantly US dollar-denominated environment.
Pfuma said demand for modern warehousing and distribution facilities continued to exceed supply, partly because much of the existing industrial property stock in established locations was ageing and poorly configured for contemporary logistics requirements. National retailers, manufacturers and distributors were increasingly seeking build-to-suit developments and sale-and-leaseback arrangements.
The fund identified high borrowing costs, limited long-term finance, tight liquidity and periodic policy uncertainty as constraints on the property sector. Construction costs also remained largely dollar-based, influenced by imported materials, energy and financing expenses.
Pfuma said the operating environment remained stable during the quarter, citing year-on-year inflation of 3.7% for the Zimbabwe Gold currency and 3.5% for the US dollar to October 2026. It argued that low inflation and monetary stability continued to support well-located, income-producing real estate as a store of value.
Looking ahead, the fund expects festive-season trading to support retail, food and forecourt activity in the final quarter of its financial year. It is targeting total annual income of at least US$3 million and net distributable income of US$2.5 million, while monitoring currency policy, liquidity, electricity supply and fiscal measures that could affect consumer spending.
The Zimbabwe Mail’s assessment is that Pfuma’s latest figures illustrate the importance of converting investment capital into productive property assets. Although the decline in investment income has weighed on one revenue stream, the increase in rental receipts demonstrates the potential benefit of expanding an income-generating portfolio. The key test will be whether developments under construction are completed on schedule and deliver sustainable rental returns.
For Zimbabwe’s wider property investment market, the demand for modern logistics facilities and institutional-grade commercial real estate presents an opportunity for REITs to channel domestic and institutional savings into productive assets. However, the sector’s growth will depend on access to patient capital, predictable policy conditions and the ability of property funds to deliver reliable income to investors.